Showing posts with label Interest Rates. Show all posts

Monday, August 23, 2010

A Bond Bubble?

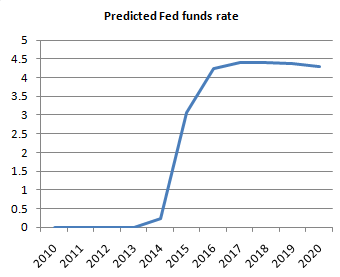
Prof Paul Krugman does not think so. Using a simplified Taylor Rule and projections for employment and inflation from the CBO he derives a predicted fed fund rate which looks like this:


Low rates for years to come!!!
He adds: "That’s right: four years of near-zero short-term interest rates. Does a 10-year rate of 2.6 percent still sound so unreasonable? And bear in mind that I’m not using some doomsayer’s forecast; I’m using the staid folks at the CBO.

And just for the heck of it, I asked what interest rate on a 10-year security would yield the same present value as investing in short-term debt at the predicted rates, and rolling it over each year. (Actually, I cheated slightly, because I was getting tired; I considered a bond in which there are no payments along the way, just repayment of accumulated interest and principal in year 10; but I’m pretty sure it doesn’t make much difference).

And the implied interest rate was … 2.6 percent.

Here’s what I think is going on: aside from the obviously intense desire of some of the bond bubble folks to see a fiscal crisis — they’ve been planning for it, and they’re not going to take no for an answer — my sense is that a lot of people just can’t bring themselves to face the reality that we’re likely to be in a zero-interest world for a long time. They just keep assuming that the Fed is going to raise rates soon, even though there is absolutely nothing about the macro situation that would justify such a rate increase."

If no bubble and the bond market is right expect some dismal economic prospects for much longer. Bu hao!

Thursday, December 3, 2009

Peak in US Unemployment in 2011?

CalculatedRisk mentions Goldman Sachs' view:
The key features of our 2011 outlook: (1) a strengthening in growth from 2.1% on average in 2010 to 2.4% in 2011, with real GDP rising at an above-potential 3½% pace in late 2011; (2) a peaking in unemployment in mid-2011 at about 10¾%; (3) extremely low inflation – close to zero on a core basis during 2011; and (4) a continuation of the Fed’s (near) zero interest rate policy (ZIRP) throughout 2011.
The peak in unemployment is much later than suggested by CR's own look at housing starts and employment and also much later than what the Fed expects. As Paul Krugman reported here: "Well, the Fed expects unemployment to come down only very gradually — over 9 percent at the end of 2010, over 8 percent at the end of 2011, around 7 percent at the end of 2012. Inflation, meanwhile is expected to remain consistently below the Fed’s target."

Zirp could well last a while longer

Saturday, November 21, 2009

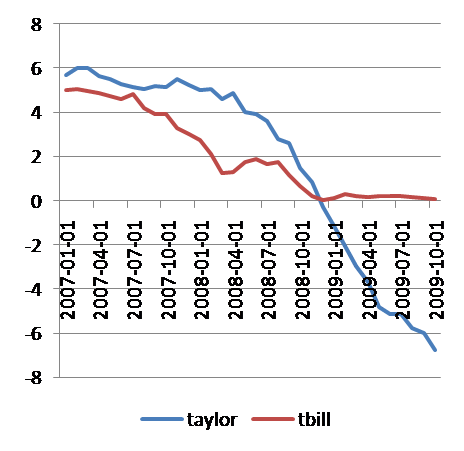
Fed Fund Rates and Taylor Rule

Paul Krugman has the chart and concludes: "Monetary tightening shouldn’t be on the agenda for a long, long time."

Monday, October 12, 2009

Krugman, Taylor Rule and Okun's Law

Very interesting post by Paul Krugman on why the Fed should not raise rates anytime soon.
Solving the Taylor Rule for a Fed Fund Target of 0% and the current inflation rate gives the unemployment rate level at which the fed should start raising rates.

The table below shows the different unemployment rates at which the fed should tighten assuming different inflation rates.

Change in PCE 0.0% 0.5% 1.0% 1.6% 2.0% 2.5% 3.0% 3.5% 4.0% 4.5% 5.0%
Unemployment 5.8% 6.2% 6.6% 7.0% 7.3% 7.7% 8.1% 8.4% 8.8% 9.2% 9.6%


Mr Krugman then looks at Okun's law which says that GDP growth 2 points above potential of 2.5% reduces unemployement by 1% and concludes: "So say we have 5 percent growth for the next 2 years — which would be hailed as a stunning boom. Even so, unemployment should fall only 2.5 points, to 7.3. In other words, even with a really strong recovery (which almost nobody expects), the Fed should keep rates on hold for at least two years."